Oregon State Treasury Increases Investments in Fossil Fuel Companies

July 25, 2023

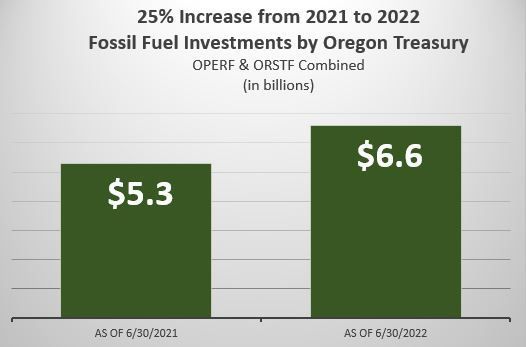
Oregon State Treasury (OST) investments in fossil fuels increased by 25% from 2021 to 2022 in the Oregon's Public Employees' Retirement Fund (OPERF) and the Oregon Short Term Fund (OSTF)
These decisions to increase fossil fuel exposure are contrary to the guidance given by Treasury’s own consultants who stated that investing more in fossil fuels increases long term risk and lowers returns.


After multiple public records requests by Divest Oregon, OST now publishes its public equity holdings and private investment funds on its website with values as of June 30 of each year. It publishes the information with a six or seven month lag. The latest data showed that fossil fuel holdings totalled $6.6 billion as of June 30, 2022 versus $5.3 billion for the same period the previous year. 


The public equity investment increase included additional investment in existing holdings and new fossil fuel holdings. The Treasury also committed to make at least a further $2 billion worth of private investments in future years, under contracts that typically last a decade.


Our Methodology 


Divest Oregon is a member of the Climate Safe Pensions Network (CSPN) which has over 20 pension divestment campaigns in the US. Through this network we partner with 
STAND.earth & Third Rail Economy to consolidate and analyze OST holdings. 


Each OPERF and OSTF holding is given a fossil fuel grouping by our partners based on its activity. Of the $6.6 billion in fossil fuel holdings as of June 30, 2022, here is a breakdown by those groupings showing an increase in each:


Group 1: Production ($1.1 billion): Oil and gas producers & explorers, and coal companies. Vertically integrated oil/gas companies, meaning companies with oil/gas reserves as well as midstream or refining operations. It was $871 million as of June 30, 2021.


Group 2: Support ($450m): oilfield services/equipment companies, refiners, pipeline and other midstream companies. It was $432 million as of June 30, 2021.


Group 3: Utility ($1.7 billion): fossil fuel power producers, electric and gas utilities. Utilities with an obvious focus on renewable energy production were not flagged. It was $1.37 billion as of June 30, 2021.


Group 4: More Fossil Fuels ($3.3 billion): holdings in companies with obvious fossil fuel interests and actions not fitting easily into groups 1-3. It was $2.56 billion as of June 30, 2021. Holdings in fossil fuel energy private equity funds are assigned here. Diversified companies included on either the
CU200 or GCEL lists are also assigned here.


Across all these groups, the investment in
NEW fossil holdings from June 30, 2021 to June 30, 2022 totaled $310 million. Examples of these new holdings include: 

  • China Coal & Oil Fields in which OST invested $2.6 million 
  • Qatari energy groups received a $2.5 million investment. 


Increases in fossil fuel holdings went up, not just increases in past holdings' share values. Following are just three examples of
additional acquisitions in fossil fuel company shares:


Chevron CORP

  • 264,204 shares on June 30, 2021 (valued then at $28 million) in OPERF Public Equity
  • 605,422 shares on June 30, 2022 (valued then at $88 million) in OPERF Public Equity
  • There was no stock split.


BHP GROUP LTD

  • 264,929 shares on June 30, 2021  (valued then at  $9.6 million) in OPERF Public Equity
  • 1,298,335 shares on June 30, 2022 (valued then at $37 million) in OPERF Public Equity
  • There was no stock split.


CANADIAN NATURAL RESOURCES 

  • 13,600 shares on June 30, 2021 ( valued then at $0.5 million) in OPERF Public Equity
  • 545,158 shares on June 30, 2022 (valued then at $29 million) in OPERF Public Equity
  • There was no stock split.


Our information source is the OPERF Public Equity Portfolio details published on the OST website.


Determining OST’s New Private Investments in Fossil Fuel Funds


For holdings such as public equity and fixed income the Treasury provides each holding name and its market value. For private equity holdings Treasury provides each holding name and its capital commitment, total capital contributed, and “fair value”. It is important to track the amount of commitments OST makes to private equity funds. These commitments represent significant long term obligations that tie up OPERF funds for a decade or more, making it impossible to respond to developments like climate risks and geopolitical shifts. 


One such example of OST’s new investments in fossil fuels include their $250M investment in Advent International GPE X in 2022. Advent has many fossil fuel companies in its portfolio including: 

  • Oceana which is Colombia’s largest crude oil transportation system
  • BOS Solutions: Leading full-service provider of drilling fluid treatment and recovery solutions to oil and gas exploration and production companies 
  • Bill Barrett Corp: a Colorado oil and gas exploration company. 


Divest Oregon reviewed OIC meeting minutes to determine what additional private investment commitments have been made to funds that invest in fossil fuel since June 30, 2022.  From July 2022 through March 2023 OST committed an additional $2 billion to private equity funds that had obvious investments in fossil fuels.  The figure is likely much higher, but the secret nature of private equity funds makes it impossible to gather all the facts. 


Four of the funds that enjoyed commitments by OST (Blackstone Energy Partners, Encap Flatrock Midstream, Global Infrastructure Partners, and NGP Natural Resources) are featured in the Private Equity Stakeholder Project’s (PESP)
Private Equity Dirty Dozen report, which profiles some of the most destructive fossil fuel investments of the world’s top private equity firms. Divest Oregon has repeatedly pointed out the numerous problems with private equity, and published the report Oregon Treasury’s Private Investment Transparency Problem to provide more details to the public, especially PERS members. The secret nature of private equity poses a significant problem when assessing OST’s fossil fuel exposure because we are blocked from knowing the details of what each private equity fund invests in. Our analysis  provides us with a representation of the private equity funds with known and significant fossil fuel exposure, but we know it is not all inclusive.  There is more, and OST continues to invest significant PERS funds in fossil fuels. 


Divest Oregon will continue its campaign to hold OST accountable for its risky fossil fuel investing and demand that decarbonization strategies be implemented  immediately.
October 13, 2026
When Will the Oregon Treasury Comply with the COAL Act? Divest Oregon’s COAL Act passed in 2024. The statute mandates annual reporting by the Oregon State Treasury (OST) to the Legislature “on actions taken pursuant to the act.” The COAL Act spells out that OST can only remain in a thermal coal investment if the company is transitioning to clean energy on a reasonable timeline. A full report under the COAL Act would document where each coal company is in its transition process, when OST expects it to be completed, and actions that will be taken if the transition is not occurring. The Treasury’s 2025 Net Zero Plan Progress Report does not comply with the statute. Table 5, shown below, was presented with this text: Staff determined that as of November 30, 2025, the portfolio had $15 million worth of investments in 12 securities identified as “Thermal Coal” companies, a decrease from $28,979,710.04 worth of investments in 21 securities reported by staff in 2024. p. 26 Divest Oregon promptly pointed out (p. 16) the contrast between the report and the statute.
September 25, 2026
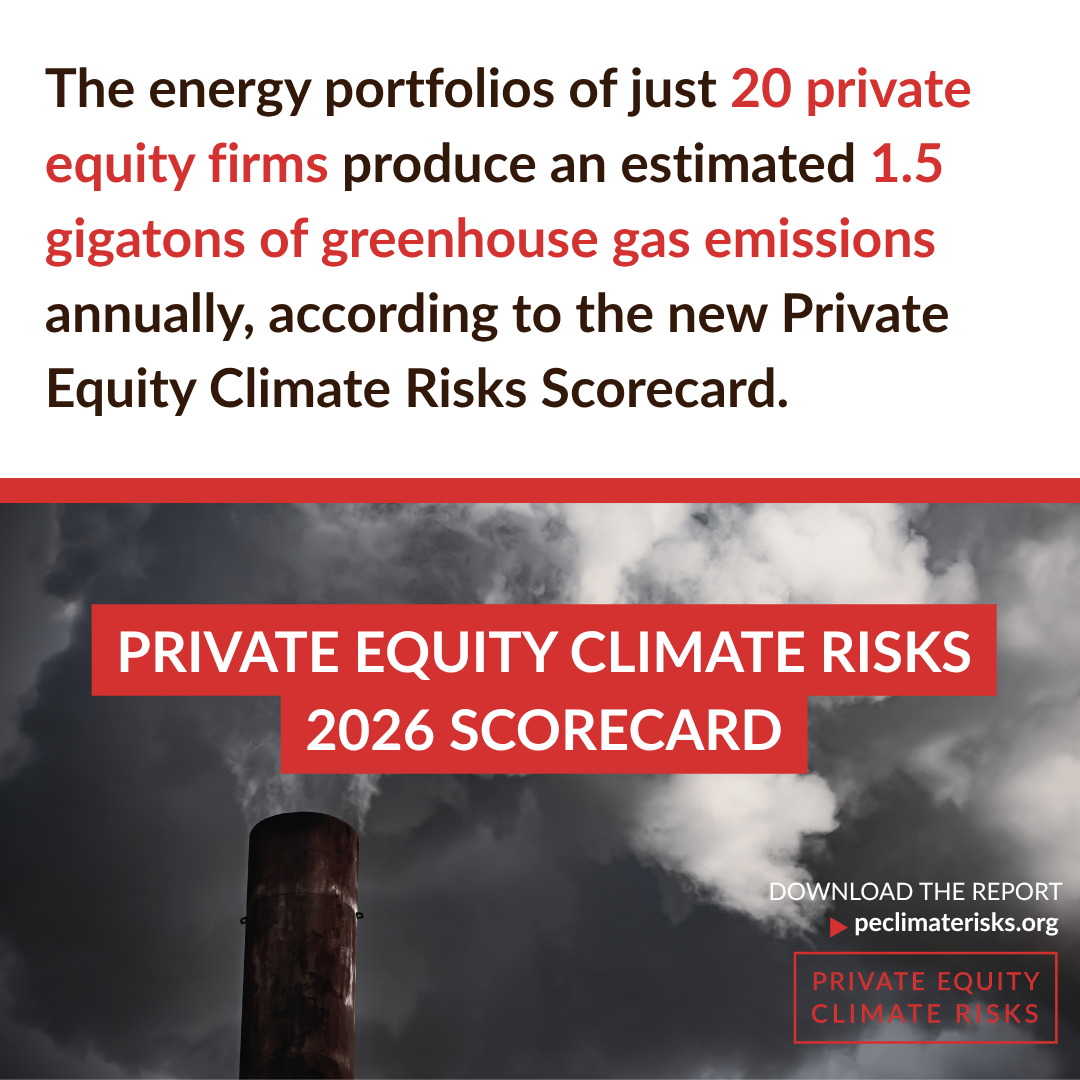
Global emissions are up. Private equity is a culprit – and so is the Oregon Treasury. Private Equity Climate Risks consortium has just published its latest scorecard and report , endorsed by 21 organizations working on climate, environmental justice, financial accountability, and consumer issues, documenting (pages 10-28) that: ⚠️ 20 private equity firms’ energy portfolios: are responsible for producing an estimated 1.5 gigatons of greenhouse gas emissions annually. include more than 1,000 assets: 244 energy companies 250 oil and gas fields 15,000 miles of pipelines 35 LNG terminals 13 coal terminals dozens of LNG tankers hundreds of fossil fuel power plants. The Guardian (9/15/2026) on the Private Equity Climate Risks report: World’s top 20 private equity firms produce more greenhouse gases a year than most countries, report finds : Firms manage $7.3tn in assets and could afford to transition away from fossil fuels yet invest in natural gas and coal-fired plants to power datacenters. “Private equity firms have emerged as the largest datacenter owners outside  of big tech.” (See the case study on data centers starting on p 25 of the report.) What about Oregon? ⚠️Six private funds, held by the Oregon Treasury, hold at least 473 fossil fuel assets. These firms are: Blackstone, Brookfield Asset Management, Encap Investments, EQT, Global Infrastructure Partners (GIP), Quantum Capital. All are in the Real Assets holdings. As Private Equity Stakeholder Project commented to the Oregon Investment Council (see Public Comment book of 9/2/2026 , page 8): Through existing OST fund commitments, OPERF likely has exposure to many of these 473 fossil fuel assets, which also create global climate risk. Some funds held by OST are making new investments in fossil fuels, pushing the pension fund further from Oregon’s Climate Resilience Investment Act (CRIA) goals and creating more risk for the fund. One example: BlackRock’s GIP. Oregon invested in GIP (Global Investment Partners fund), created to finance a new LNG terminal (see Is the Oregon State Treasury Supporting Environmental Racism in the Gulf South? Divest Oregon 9/26/2024). The fund is now managed by BlackRock and it plans to acquire AES, a massive US-based utility company that also backs 23 fossil fuel-fired power plants globally. If the AES deal closes, BlackRock’s GIP will nearly double its fossil fuel power plant portfolio to 50, spanning 11 countries.
August 6, 2026
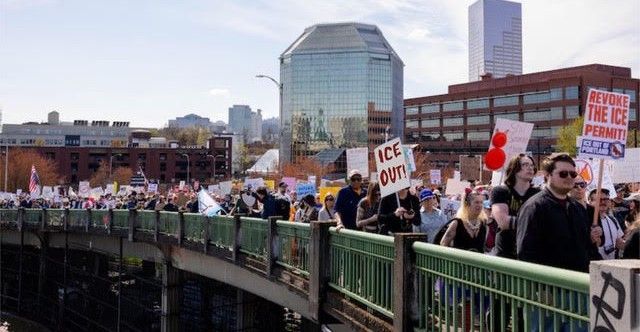
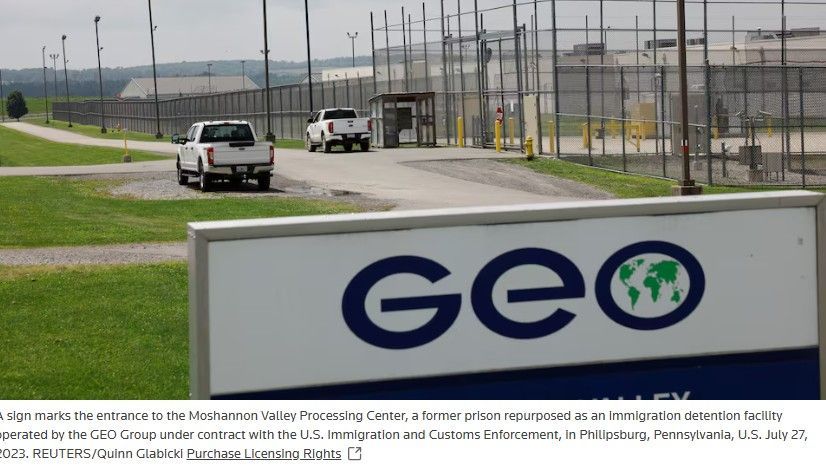
“As a PERS beneficiary, I am horrified that my pension funds private prison contractors and ICE detention centers.” Three recent Letters to the Editor of The Oregonian voice deep disquiet that the Treasury invests in immigrant detention facilities and spyware that are internationally recognized as engaging in human rights abuses and are flagrantly violating constitutional rights – instead of constructive investments. In June 2025, Oregon Treasury data shows investment of $51 million in CoreCivic and Geo Group, private prison contractors, and Palantir, maker of surveillance software used by ICE against US residents. Divest Oregon has been asking the Treasurer for years : Why aren’t investments screened to comply with Oregon Investment Council standards? See the blog: Why is the Treasury still investing workers’ retirement in fossil fuels, ICE contractors, and surveillance technology? for the backstory. In May, Treasurer Steiner stated that Treasury used its shareholder power to vote against four candidates for Geo Group’s board of directors because it was not conforming to Treasury’s investment standards – but kept the stock: Treasurer Steiner is “ deeply troubled ” about ICE contractor Geo Group…but OST has been a shareholder for years. The Treasury is investing public employee money. It has a responsibility to the beneficiaries and to all of us to follow its own investment guidelines. The letters voice a strong call for change: PERS should divest from ICE-contract prisons ( PDF , The Oregonian 7/27/2026) “Human Rights Watch reports that 52 people died in the custody of U.S. Immigration and Customs Enforcement in the first 500 days of President Donald Trump’s second term…." “It is tempting to feel powerless about this senseless waste of life. But here in Oregon, we have an opportunity to make a difference. We can demand that the Oregon Public Employees Retirement System divest from The Geo Group and Core Civic, two of the largest for-profit private prison corporations, which contract with ICE to run immigration detention facilities.” Oregon shouldn’t invest in ICE prisons ( PDF , The Oregonian 7/31/2026) “As a PERS member, I am not comfortable profiting from other people’s misery, and I am confident that others feel the same." “Reduced public investments and increased public awareness could even make investments in Geo Group and CORE Civic less attractive. Oregon should lead opponents of the cruelty in this immigration crackdown, epitomized by these prisons." Divest PERS from ICE-contract prisons ( PDF , The Oregonian 8/3/2026) “As a PERS beneficiary, I am horrified that my pension funds private prison contractors and ICE detention centers." “Oregon State Treasurer Elizabeth Steiner said she was 'deeply troubled' by Geo Group’s practices, and that the Treasury had used its shareholder power to vote against four candidates for the company’s board. Has that vote had any noticeable effect? Will Geo Group change its business practices as a result? These companies might take notice if the Oregon Treasury began pulling its investments.” “Like the people of Minneapolis, Oregon Gov. Tina Kotek, Oregon Attorney General Dan Rayfield and Portland Mayor Keith Wilson stood up to ICE. This is the moment for our Treasury staff to show the same courage."
July 6, 2026
Photo by SpaceX on Unsplash In a July 1 article Reuters reported that Oregon Treasurer Steiner wanted guidance from the federal Securities and Exchange Commission (SEC) about SpaceX. How should pension funds handle the new company with the giant market valuation? SEC Commissioner Mark Uyeda answered Elizabeth Steiner in an interview in Reuters . One takeaway is his simple point that if you don't like the governance arrangements of a stock, don't buy it. A message from the SEC's Uyeda: If you don't like SpaceX's governance, don't buy the shares ( Reuters Sustainable Finance , July 1, 2026) Note: The Oregon State Treasury has $6.8 million in exposure to SpaceX through one public equity index fund and one global equity portfolio ( Portland Business Journal July 2, 2026). Divest Oregon has made the same point to Treasurer Steiner, repeatedly. For example, Treasurer Steiner posted on Facebook on May 6, 2026 that she is “deeply troubled” by the ways ICE contractor Geo Group fails to adhere to Oregon Investment Council (OIC) policy. Divest Oregon responded : The Oregon Treasury has held stock in private prison/immigrant detention contractors for years, in spite of well-publicized abuse. If a company is violating OIC policy the Treasury has an obligation to sell the stock. In fact, Treasury’s screening process can and should prevent purchasing or holding stock that violates OIC/Treasury standards. The SEC Commissioner quoted in the Reuters ’ interview about SpaceX also says pension funds have the duty and ability to do such screening: Question by Reuters to SEC Commissioner Uyeda: "You write that ‘If prospective investors have concerns with the governance arrangements, then their most powerful tool is to not purchase shares of the stock.’ But critics like some big pension funds say the fast-track addition of SpaceX to big indexes could make them unwilling buyers of the stock. What would you say to such critics? Response from SEC Commissioner Uyeda: "Large pension funds have choices with respect to ​their investment decisions as part of their fiduciary duty to the plan. While index funds may have certain conveniences and low costs, there is a trade-off to outsourcing securities selection to a third party. There are alternatives, such as selecting a fund that follows a different index or is actively managed, or engaging in customized direct indexing that would provide more control over the portfolio.”
May 19, 2026
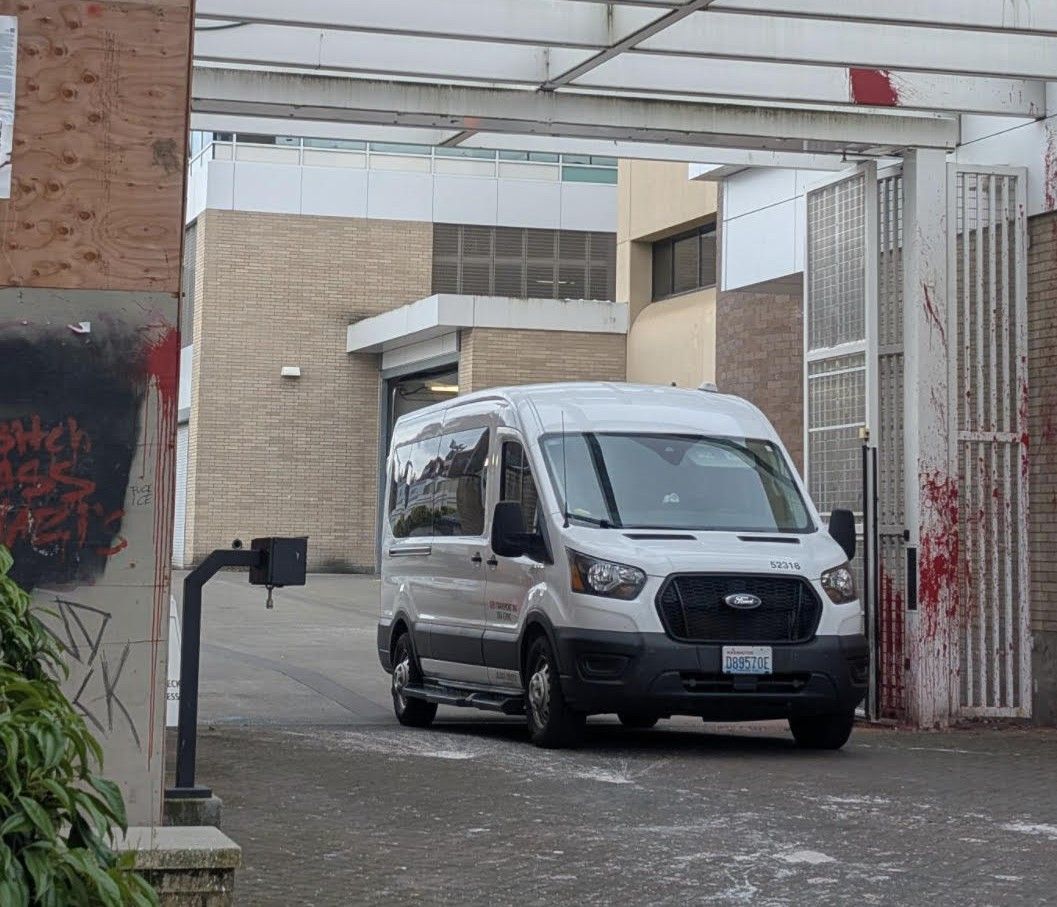
A Geo Group van leaving the Northwest ICE Processing Center in Portland Oregon. May 2026
April 9, 2026
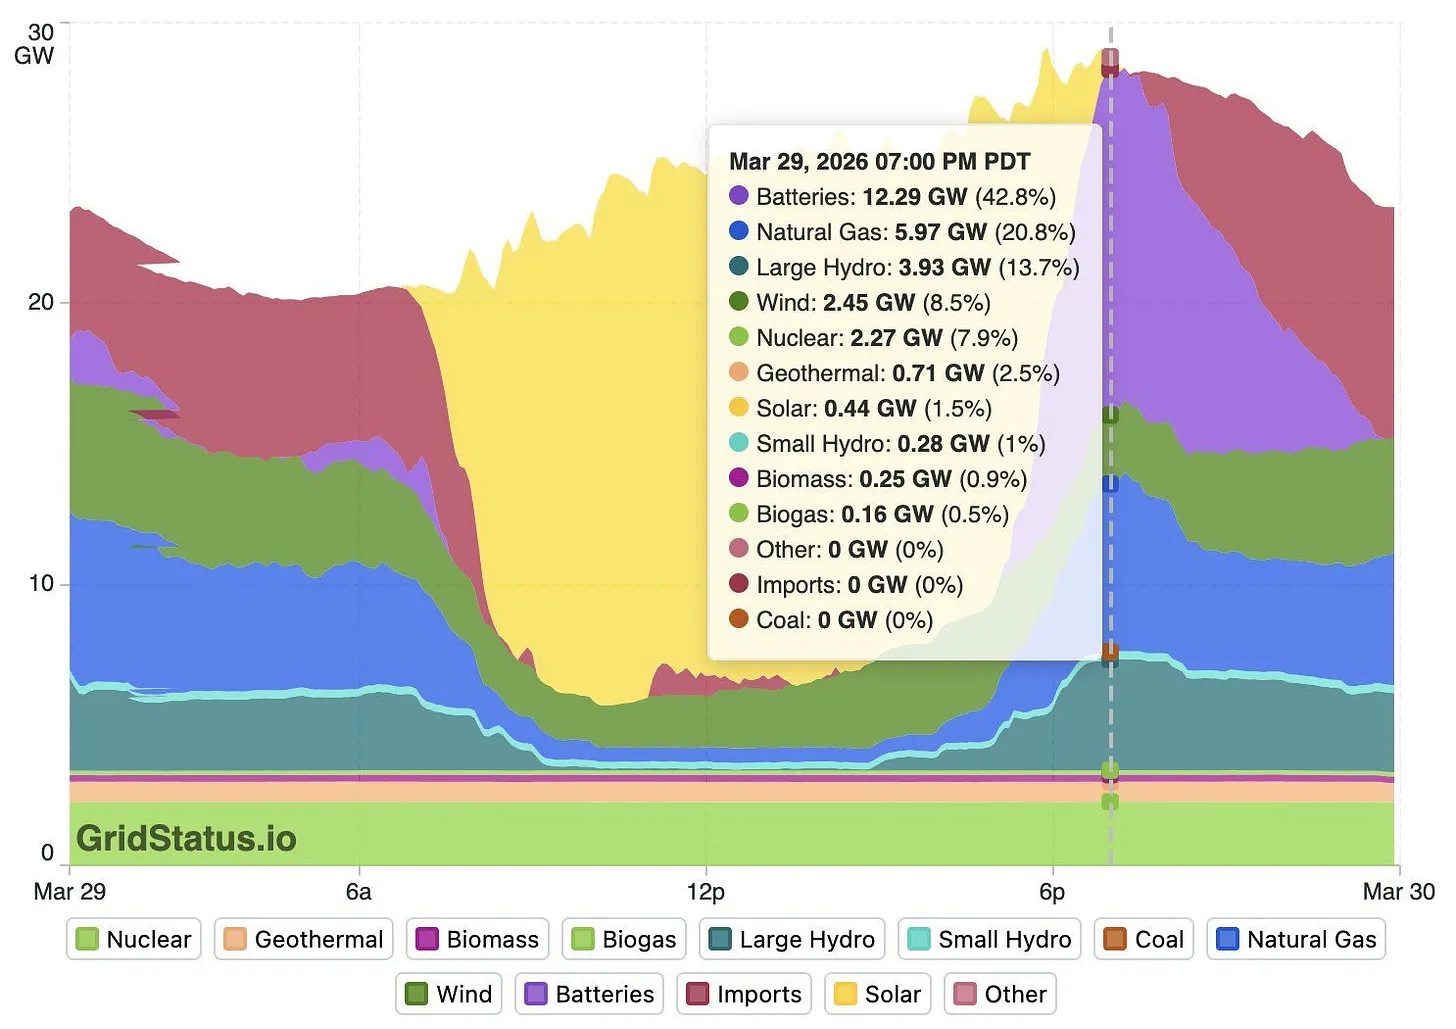
At the March 2026 OIC meeting, John Goldstein from Goldman Sachs spoke of the strength of renewable energy stocks (recap in Net Zero Investor 5/3/2026 ). Bill McKibben shows us how the sector is evolving with battery technology advances. Night into Day ( The Crucial Years substack 3/30/2026): “For the first time, the United States now has the capacity to supply 100% of domestic energy storage project demand with American-built systems,” said Noah Roberts, executive director of the U.S. Energy Storage Coalition. “That is a fundamental shift from where we were just a year and a half ago, when the majority of battery storage systems were imported.” “Already, the U.S. has enough capacity to meet demand for finished grid battery enclosures…. By the end of this year, the U.S. will also achieve self-sufficiency in a higher-value part of the supply chain: the battery cells themselves. It’s a major industrial coup that is bringing thousands of high-tech manufacturing jobs to communities across the country.” Solid-state batteries are becoming a possibility; they promise to solve several problems: “Batteries are now being tested by multiple companies that can go 800 miles on a single charge….“In September, Mercedes drove a modified EQS over 1,200 km (745 miles) using 106 Ah solid-state battery cells supplied by US-based Factorial Energy. Factorial launched the first commercial solid-state battery program in the US …earlier this year.” The Finnish company Donut Labs shows where this is heading: “The Donut batt can charge to full in five minutes…; has a practically unlimited lifespan (100,000 charging cycles); is unaffected by heat and cold (-30C to 100C); and contains no rare earth, precious metals or flammable liquid electrolytes. With all that, Donut Lab says it will be cheaper to produce than conventional lithium-ion batteries…” “And the technological miracles are only beginning. For instance, Christopher Mims reported last week in the Journal on a new round of ‘thermal batteries that store solar power as heat instead of electricity, perfect for use in high-temperature industrial processes.’” “Marija Maisch was reporting in January that…salt-based batteries are nearing price and performance parity, if not for cars then for utility scale batteries.” And this chart shows the surge of batteries coming online as solar installations lose sunlight. Night into day.
March 17, 2026
A question from Divest Oregon, a coalition of a hundred organizations with strong PERS representation, remains unanswered: What screening process does the Oregon State Treasury (OST) use, if any, when investing PERS funds or choosing investment managers? Is the Treasury screening investments in fossil fuel companies? Andrew Bogrand, Divest Oregon’s Communications Director, spoke at the Oregon Investment Council (OIC) in January 2026. He noted that investment in fossil fuels contributes to global instability, using Venezuela as an example. (See this blog .) The current Iran war emphasizes this point. Andrew regularly comments on the ties between insecurity and fossil fuels as a policy lead for human rights and natural resource justice at Oxfam. The argument that fossil fuel investments are a sensible diversification of a portfolio has long been outdated. But looking at the most recently published June 2025 public equity and fixed income data, the Treasury is still investing in fossil fuels. Under fiduciary duty and the Climate Resilience Investment Act ( CRIA ), the Treasury must move to alternative investments that align with the reality of climate change and a rapidly destabilizing world. Is the Treasury screening investments prone to legal liability, human rights abuses, or reputational risk? In an April 2023 report , Divest Oregon called out the Treasury's investment in private prisons and surveillance technology as context for the question: Does the Treasury have a screening process? If so, what is the screening process? One example given in that report was the NSO/spyware technology that OST heavily invested in. The Guardian reported extensively (2022) on the OST’s investment in NSO/Pegasus spyware: “However, it now appears that the Oregon pension fund, one of the most prominent in the US, gave its tacit approval over an investment in NSO several years ago – at a time when security researchers were already publicly raising alarms about the company.” In a more recent report, Oregon Treasury’s Investment Screening Failures ( October 2025 ), Divest Oregon again questioned the Treasury’s investment screening process. Examples of questionable investments included GEO Group, CoreCivic, and Palantir. Investments in GEO Group and CoreCivic fund private prison contractors and ICE detention centers. Investment in Palantir funds ICE surveillance software used against US residents. See additional information below for each of these companies. The most recent public data ( June 2025 ) shows that the Treasury continues to invest in these private prison and surveillance technology companies with a long history of human rights abuses and legal vulnerability. These companies are central to the current federal administration’s construction of a police state and its massive violation of due process. See Trump’s Mass Deportation Campaign ( The New Yorker 3/15/2026). For example: Recent private prison contractor GEO Group news: In February 2026, the Supreme Court found that GEO Group, a private prison operator running an Immigration and Customs Enforcement (ICE) facility, cannot claim governmental immunity from lawsuits for violating human trafficking laws, even if those violations were under government orders. Recent surveillance technology company Palantir news: In Portland, now, Palantir’s Elite app is being used to identify potential deportation targets, generate dossiers on individuals and provide a “confidence score” on the person’s address. ( The Guardian 3/13/2026) Why should the Treasury screen its investments? Screening is necessary to avoid investments that contravene Treasury standards, OIC policy, legal standards including fiduciary duty, or Oregon State law. For instance: The Oregon Department of Justice has recently opened an inquiry as to whether OST investment in companies with contractual ties to ICE violates the Oregon Sanctuary Promise Act of 2021 . The CRIA Act of 2025 mandates that the Treasury: -- “actively analyze and manage” climate risk to the portfolio -- report on its progress toward investing in public equity holdings that incorporate the tenets of a just transition in their overall priorities and portfolio
February 18, 2026
Part 2: Building on Oregon State Treasury’s 2025 Progress toward Net Zero Emissions Divest Oregon applauds initial action, offers recommendations for future reporting, including the use of multiple metrics
February 18, 2026
Part 1: Building on Oregon State Treasury’s 2025 Progress toward Net Zero Emissions Divest Oregon applauds initial action, offers recommendations for future reporting, including the use of multiple metrics