Treasury’s Love Affair with Private Investments Doesn't Add Up

August 25, 2025

Treasury’s Love Affair with Private Investments Doesn’t Add Up


Two recent, major investigations by
The Oregonian and the Oregon Journalism Project in Willamette Week and statewide local newspapers, recently detailed significant problems with the Oregon State Treasury’s private equity overexposure for PERS. 


Following these publications, Divest Oregon has received questions about the information and risks of this exposure, which our coalition has tracked with concern for years. In this memo, we provide answers.


By standard financial yardsticks, Treasury’s private equity investments in the past 13 years routinely underperformed the benchmark long established by the Oregon Investment Council (OIC).  They regularly underperformed the broad US stock market. They have not provided exceptional returns. Simply put, Treasury’s love affair with private equity no longer adds up.


OPERF’s 10-year rolling average private equity returns are substantially below OIC’s benchmark


OIC Investment Policy 1203 (at p.11) says that OPERF's private equity allocation is managed to produce net excess returns “over very long time horizons,
typically rolling, consecutive 10-year periods”  (emphasis added). 


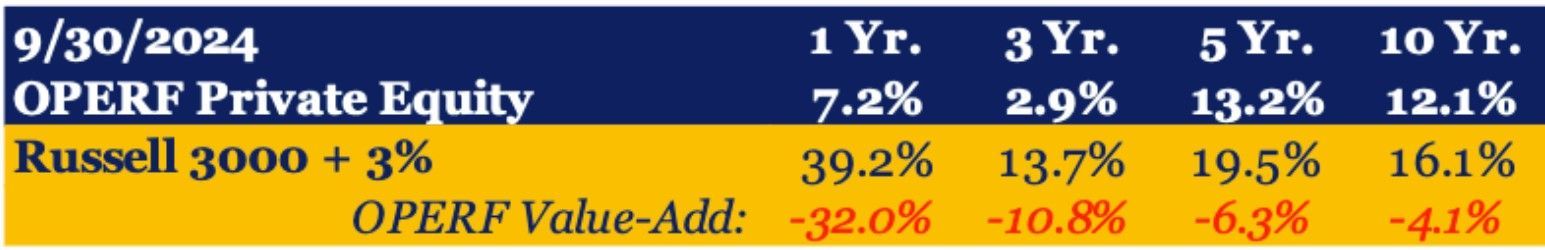
Below are the 1, 3, 5 and 10-year third-quarter private equity rolling returns Treasury presented to the OIC at its
1-22-2025 meeting, at p.59. All OPERF 1, 3, 5 and 10-year rolling returns are below OIC’s benchmark (Russell 3000 stock index + 3%) by substantial amounts, though Treasury's website at p.9 says 1-year stated returns are not meaningful.

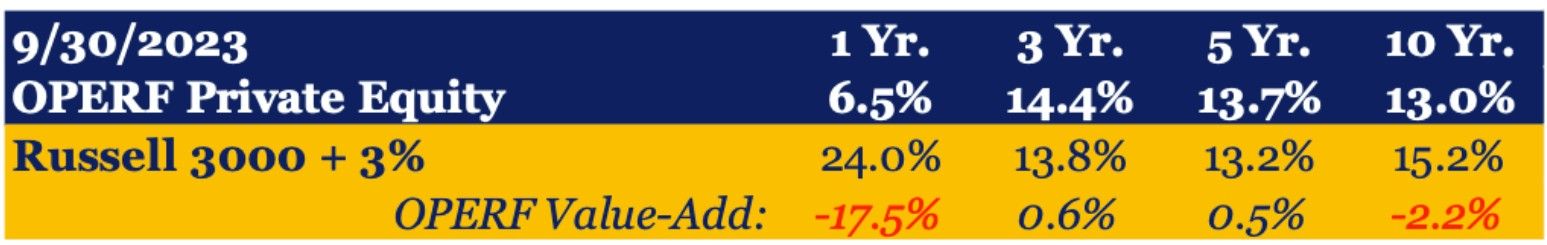
Here is the same data for the previous year, 2023, at p.35. The amount compared to benchmark is slightly positive over 3 and 5 rolling years, and substantially negative over 10 rolling years.

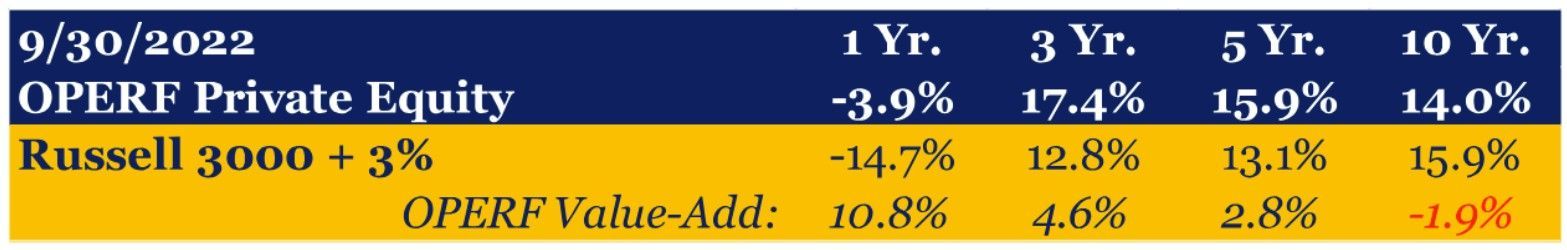
In 2022, the year before that (at p.16), the 3 and 5-year returns are substantially positive, but the 10-year rolling return is substantially negative.

In 2021, the year before that (at p.29), the 5 and 10-year returns are substantially negative. 
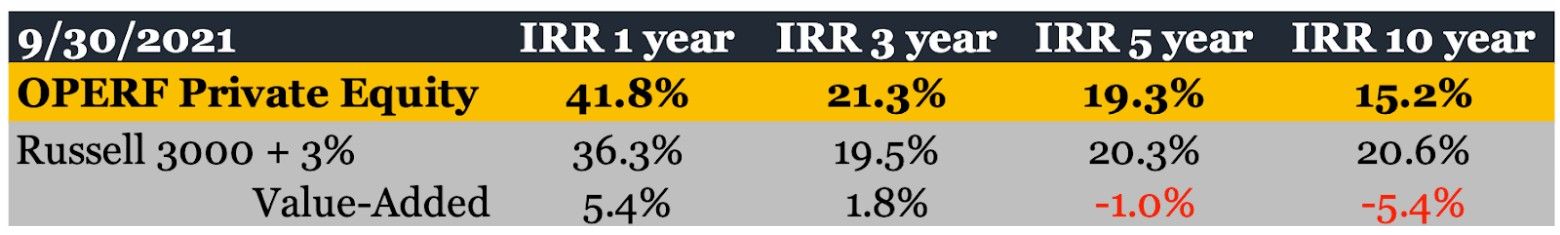
Note the “IRR” designation of returns above, which means the estimates are of an “Internal Rate of Return.” This is the common method for stating Treasury’s private equity returns. However Treasury's website at p.9 warns: “Due to a number of factors . . . the IRR information in this report DOES NOT accurately reflect the current or expected future returns of the partnership. The IRRs SHOULD NOT be used to assess the investment success of a partnership or to compare returns across partnerships.” (emphasis added).


This points to real problems with how OPERF values its private equity investments. If you are confused about why Treasury would state values in one place that it calls unreliable in another . . . so are we.


Two-thirds of OPERF private equity’s 9 most recent consecutive 5-year rolling averages failed to meet benchmark 


In addition to the performance failures documented in the last four consecutive 10-year rolling averages, we were able to calculate the results of the 9 most recent consecutive 5-year rolling averages from data that OIC consultant Meketa presented to the OIC. 


The data is annual year-end comparisons of OPERF’s private equity returns with its Russell 3000 index + 3% benchmark, for years 2012 through 2024,
here (p.77) and here (p.84). Meketa presented the data in OIC meeting materials and Treasury can not disavow them. (Calculation results show some differences with the 1, 3 and 10-year rolling returns presented above. That is because those returns are based on third quarter numbers, not year end numbers.)


The Meketa-presented data allows the calculation of the most recent 9 consecutive rolling 5-year averages: 2012-2016, 2013-2017, 2014-2018, 2015-2019, 2016-2020, 2017-2021, 2018-2022, 2019-2023, and 2020-2024.
The Meketa numbers show OPERF’s private equity returns failed to meet benchmark in 6 of the 9 rolling 5-year averages. In 5 of those 9 averages, private equity even failed to meet the return of the Russell 3000 index—not the 3 percentage points higher which is the standard. 


This means OPERF’s private equity performed
worse than a broad US stock market index during more than half the rolling averages examined. That is not high performance as has been so often touted by Treasury management and staff.

On average over the entire past 13 years, private equity failed to even meet the Russell 3000 index


Tellingly, OPERF’s private equity on average over the entire 13-year period failed to meet benchmark (Russell 3000+3 percentage points) and even failed to meet the Russell 3000 index. According to Meketa’s numbers, OPERF’s private equity average return over 13 years was 13.29%; the Russell 3000 average was 16.37% and the 3% higher benchmark average was 19.37%. 


This means
OPERF’s private equity performed worse than a standard stock market index over the entirety of the past 13 years, and underperformed its benchmark by a whopping 31%. Over the past 13 years OPERF would have earned 40% more on the money it put into private equity (3.08% annually x 13 years; 47% with compounding) if Treasury had put its PERS beneficiaries’ money into the standard stock index fund OIC chose as a base for comparison. Instead, staff disregarded policy and continuously steered OPERF into increasing amounts of private equity—with all its overt and covert fees and costs, secrecy, complexity, illiquidity, and economically undesirable and even destructive side effects.


This is a
spreadsheet of our benchmark calculations.


For the past 7 years, Treasury staff disregarded its OIC-mandated investment range for private equity 


In OIC meetings, Treasury has contended that everything is proper because even though it continues to substantially exceed its target for private equity investments, private equity’s 26.5% share of OPERF is within OIC’s approved “range” of 17.5%-27.5% of OPERF’s portfolio.


Treasury omits saying that ranges are established in order to “balance the desirability of achieving precise target allocations with the various and often material transactions costs associated with . . . rebalancing activities.” (OPERF Investment Policy Statement p.12.)


But there are no transaction costs to slowing the growth of private equity in the portfolio by buying less of it. Transaction costs occur only from sales of existing holdings in the secondary market. And Treasury staff has been pushing the upper range for ever-expanding private equity investments
from 2015 until recent slowed commitments and the $4.5 billion in value- depressing secondary sales reported by The Oregonian.


OPERF monthly returns and asset allocations, available on Oregon Treasury’s website, show that in 2018 the OIC-approved range for private equity in OPERF was 13.5% to 21.5%—the target of 17.5%, plus or minus 4%. They further show that staff exceeded that range in the fourth quarter of 2018 when OPERF had 22.1% of its portfolio in private equity.


For the next 3 years, in every quarter but one, Treasury management allowed staff to exceed its OIC-approved private equity range. By the third quarter of 2021, OPERF was almost 9 percentage points above its target and 5 percentage points above its upper range.


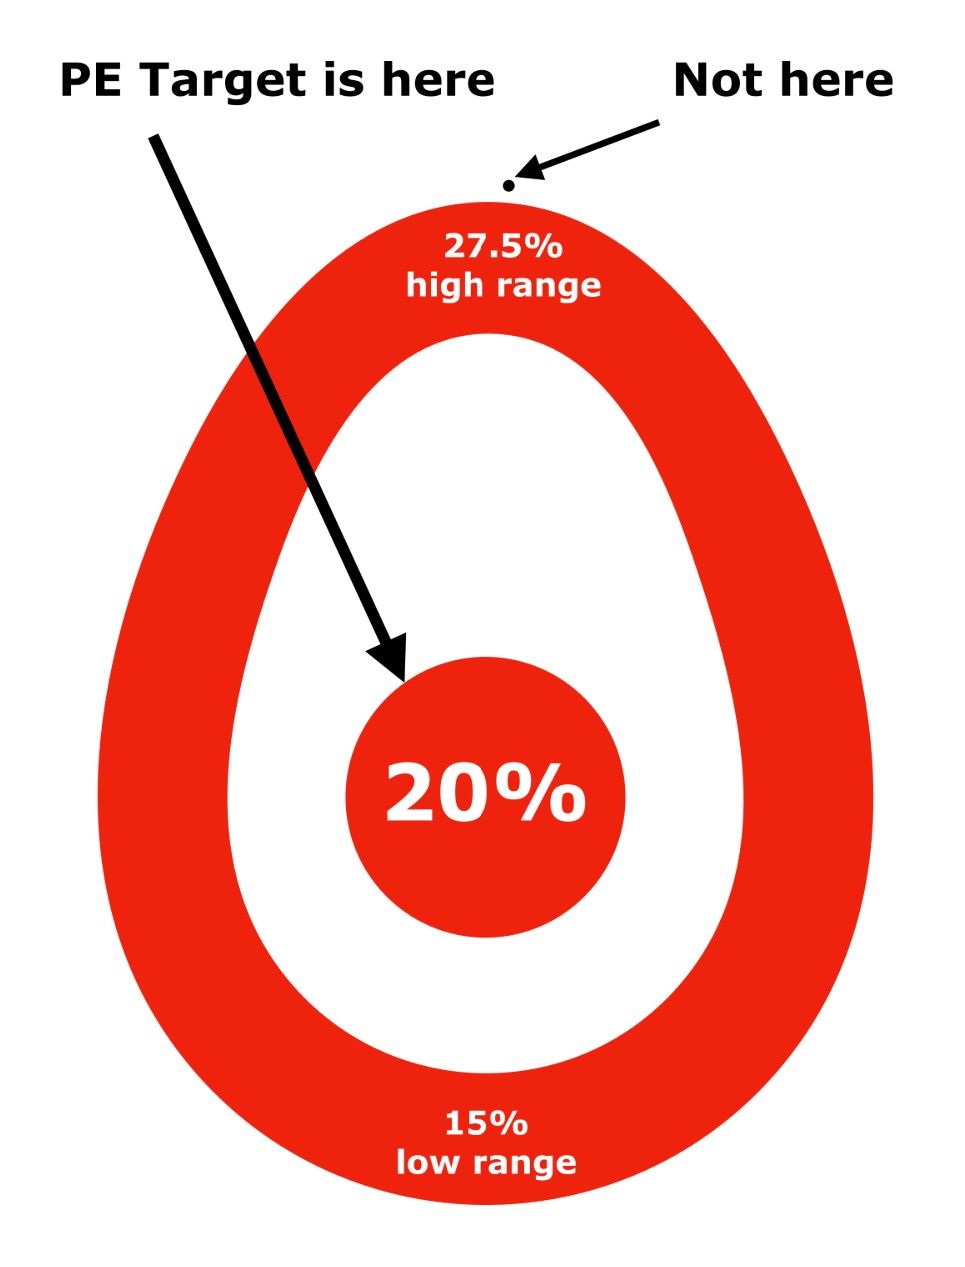
There were no real brakes on this growth. In the fourth quarter of 2021 OPERF’s private equity came within the upper range–but only because the OIC increased the upper range from 21.5% to 27.5%. And the new private equity range, unique among OPERF asset classes at the time, was itself imbalanced. Rather than plus or minus the same number around the target, the OIC skewed the range to be 7.5 percentage points above the increased 20% target, and 5 percentage points below it (as graphically represented in the figure below). The accommodation to staff’s profligacy is obvious.
Treasury remained resistant to lowering allocations even as the problem of misallocation loomed. 


At a November 2022 OIC meeting, Treasury management sought to solve the misallocation problem by again raising the private equity target, from 20% to 22%. After Chair Samples expressed her disapproval,
management said (at 58:45) “I could tell you candidly whether it's 20 or 22 it makes no difference to us. We’re still going to be executing the same plan.” At the OIC’s January 2023 meeting, management described (at 1:26:30) OIC’s private equity policy target as “artificial”: “I don’t think we as an organization are in a rush to get down to 20 percent. We hope to get there in time, but understanding what you’re saying, your question, we don’t want to lose the long term value of what we're doing   in order to get to some 20% artificial number.”


From October 2018 through September 2021, Treasury management allowed private equity to exceed the upper range of OIC approval in 11 of 12 quarters. After the OIC then increased the upper range, Treasury management and staff still exceeded it in 7 of 15 quarters. And if the OIC in 2021 had approved a range of plus or minus 5 percentage points from target—the balanced practice it usually followed—then OPERF private equity would have been
beyond the upper range in all quarters but one for the past seven years—from October 2018 until today.


Management and staff should have taken OIC policy seriously.
The signals to start a responsible path to target were readily apparent in 2015. Instead, Treasury waited  eight more years for the bottom to fall out of OPERF’s excessive private equity investments in 2023. 


While no one can always predict the behavior of future investment markets, anyone can predict that damage to pensions should be expected when pension investment policy is disregarded for years.
Had Treasury simply followed policy, rather than disregarding it, OPERF would not have incurred the $1.4 billion investment loss calculated by the Oregon Journalism Project and published in  Willamette Week.


This table shows Treasury management’s and staff’s disregard of private equity’s upper ranges from 2018-2025.


Treasury management defends its serial policy violations as good for OPERF. They’re not.


The Oregonian
quoted Treasury’s chief investment officer as saying that longstanding OIC policy expecting 3% above-market performance from high-risk private equity returns “may not be the best measure.” He contended that over the last 20 years, OPERF’s private equity outperformed the stock market by 2 percentage points and he suspected the OIC would be happy with that—even though that is a 33% reduction in OIC’s policy—expected market outperformance for private equity.


These comments do not inspire confidence that Treasury management is facing reality. The facts speak for themselves: Seven years of serial policy violations by investment staff that resulted in today’s $1.4 billion loss, and a private equity 13-year average that performed worse than the broad US stock market—making Treasury's high-fee, high-risk, illiquid bets costly losers, not index-beating winners.


OPERF’s heavy reliance on private investments raises important policy questions:


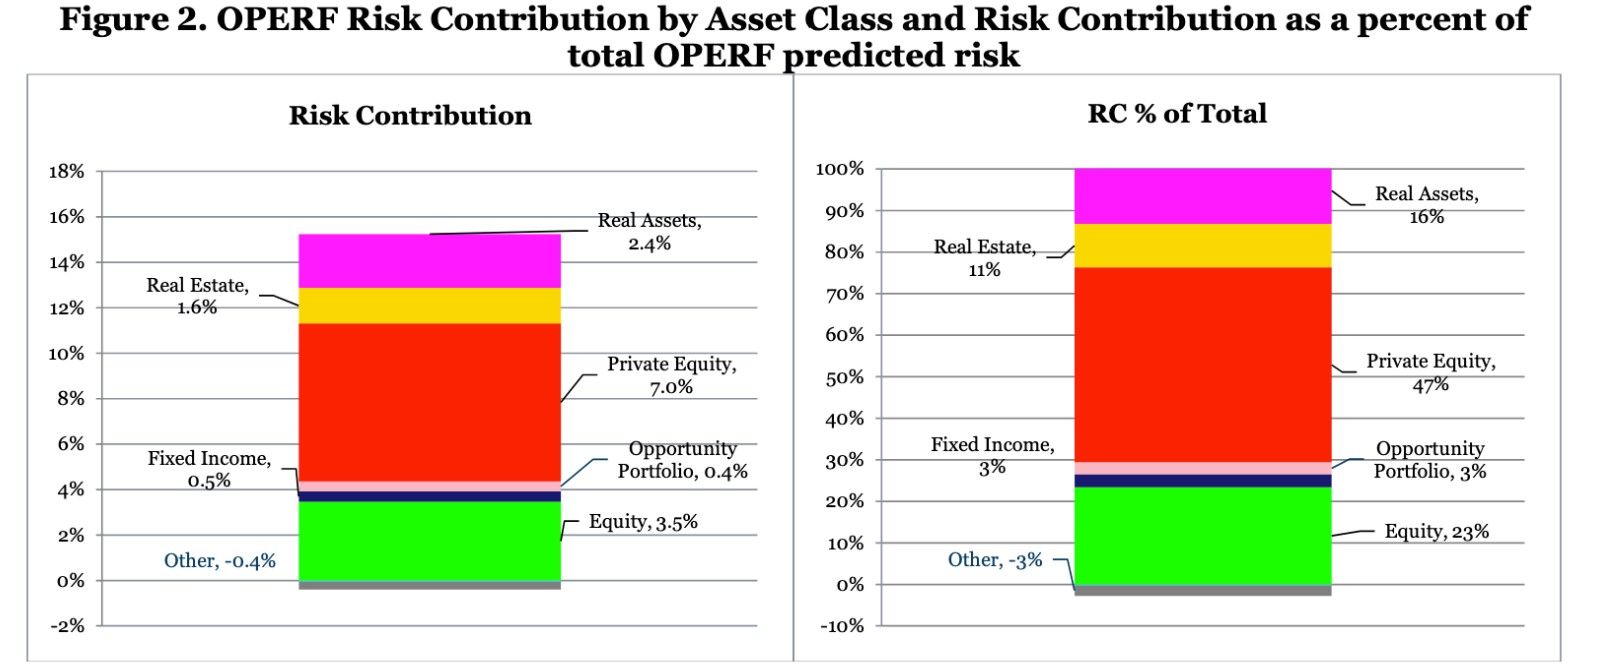
Should a responsible public pension fund invest a quarter of its assets into a class that generates almost half of all financial risk to the portfolio? That is the risk Treasury reports to the OIC (March 2025, p.102), as seen in OST’s presentation chart at below right.

Should a responsible public pension fund invest almost 60% of its assets in opaque private investments with no public oversight?  OPERF is out on a limb in this regard. Public Plans Data, an independent academic and professional consortium, reports that in 2024, state and local pensions averaged about half the amount of private equity (13.7%) as OPERF has, as well as about half the amount of overall private investments (30-33%). And a 2024 survey of 50 top pension executives found that most thought a 20-40% allocation to private assets was reasonable—while none thought more than 50% was reasonable.


Treasury’s disregard of OIC allocation policy is not limited to private equity.


Treasury’s Real Assets class, another set of secretive private investments, comprises 10.5% of OPERF, even though its target is 7.5% and its approved upper range is 10%. That puts it 40% over target, and over its top permissible range. Staff tells the OIC (at p.68) it does not expect to bring the allocation to target until 2032—7 years from now. And as seen from Treasury’s Risk Contribution chart above right, Real Assets is also an outsized risk contributor—with 10.5% of OPERF assets, it generates 16% of portfolio financial risk.
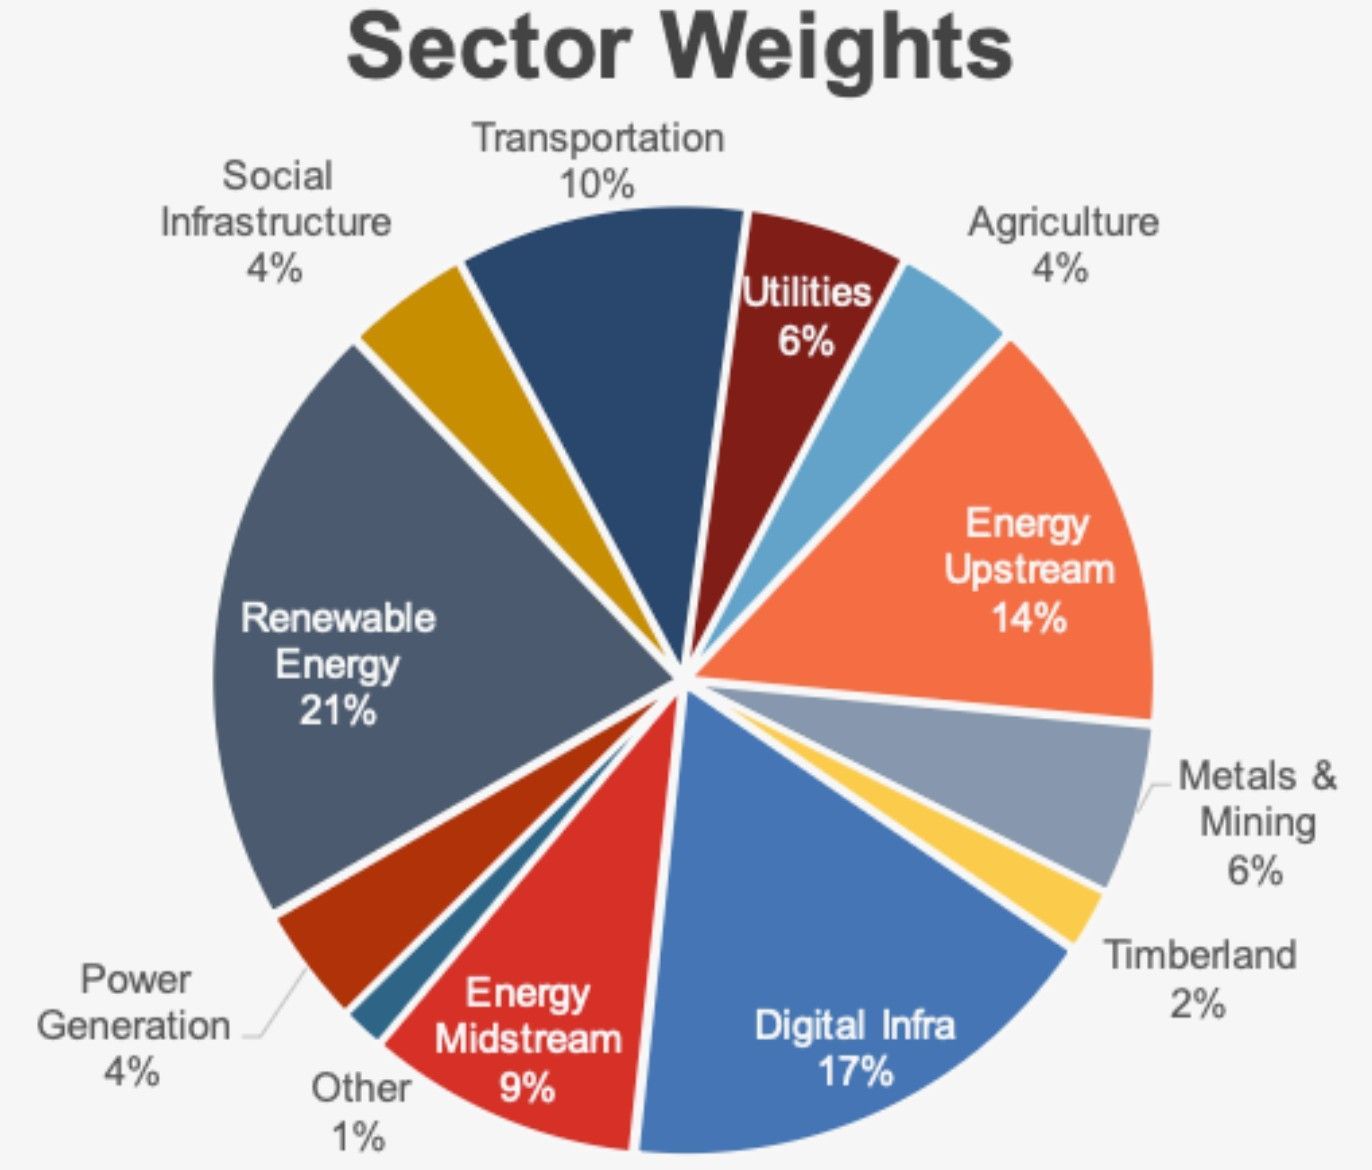

At least as importantly, much of PERS emissions intensity comes from the Real Assets class. That must be addressed immediately. As shown above from Treasury’s April 2025 presentation to the OIC (at p.54), about one third of these assets are in sectors funding fossil fuel extraction, infrastructure, and power generation. 


These OPERF investments create and cement decades-long greenhouse gas emissions. They will inevitably increase global warming that
economists now identify (at pp.15-20) as posing increasingly substantial risks to GDP and investment values. 


As shown below, Treasury’s consultant Ortec (in its 2021
Climate Scan Report at p.8) forecast a 37% reduction in OPERF values by 2060 under a failed transition—the path for which OPERF is currently investing. OST’s climate investment choices, along with other public pension funds, matter considerably to their own future returns and to future retirees.
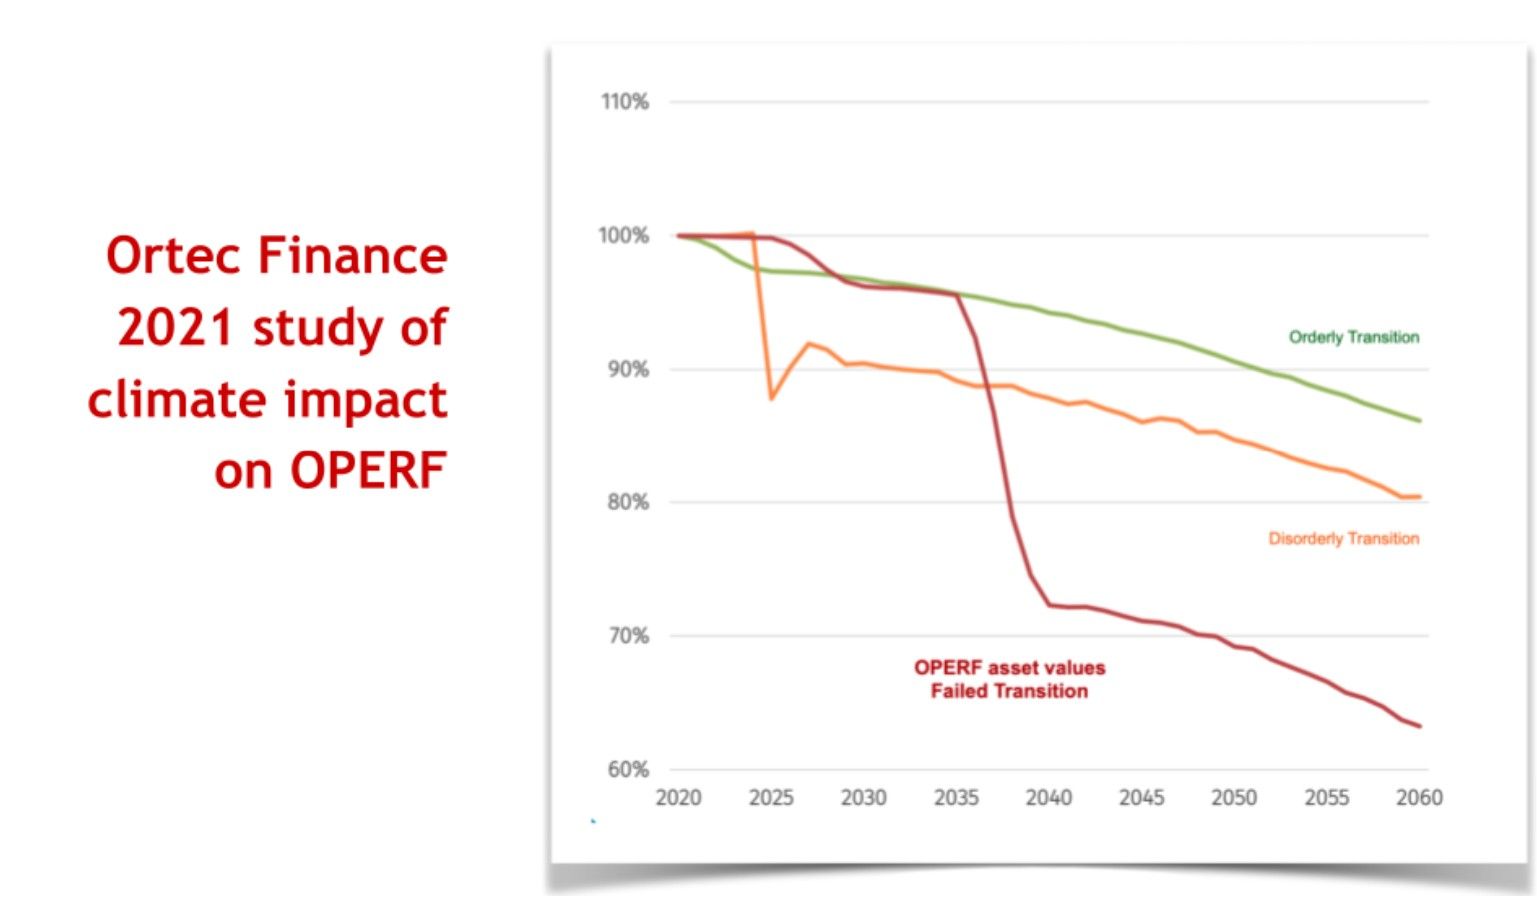
Treasury staff nevertheless ignores this substantial climate risk, and claims a history of Real Asset returns 1-2% over benchmark, presenting (at p.66) to the OIC this April an Internal Rate of Return (IRR) of 7.6% from inception of

the asset class to date. However, Treasury’s website says “IRRs SHOULD NOT be used to assess the investment success of a partnership or to compare returns across partnerships.” More accurate information on Treasury’s website shows Real Asset returns to be 4.8% from inception to date on a time-weighted basis. This 4.8% is almost 2% below benchmark.


Conclusion: An unremedied problem in Treasury’s investment culture will continue to cost PERS billions. It will also sink the Net Zero Plan for OPERF.


Treasury’s own numbers belie the contention that private equity is a high-performing asset that is worth its high risk, complexity, secrecy and illiquidity. In the past, perhaps yes, but the past is over. Experts agree that high interest rates and too much money dedicated to too many marketers from firms chasing too few deals have drastically changed the attractiveness of private equity. Simply put, Treasury management is driving private equity investment by looking in the rearview mirror.


But the problem at Treasury is more than bureaucratic inertia. Years of ingrained conduct by Treasury management and staff show they have resisted and even flouted OIC investment policy when they want. Recent news investigations pulled the curtain on a troubling and problematic investment culture in need of serious reform. 


Without reform to overcome active staff resistance to policy, PERS will not just continue to leave billions on the table. The future of the Treasurer’s Net Zero Plan, and the climate-protecting investment changes that must come from it, are in grave doubt. Prominently hanging in the balance is an end to new private investments in decades of climate-damaging fossil fuel projects and infrastructure. This was a promise made by the previous Treasurer in the Net Zero Plan, and made by the current Treasurer on the campaign trail. 


It is time for those promises to show themselves in action–beginning with a complete and public examination of how and why Treasury management and staff spent the better part of the past 10 years disregarding OIC policy on private equity investing.
September 25, 2026
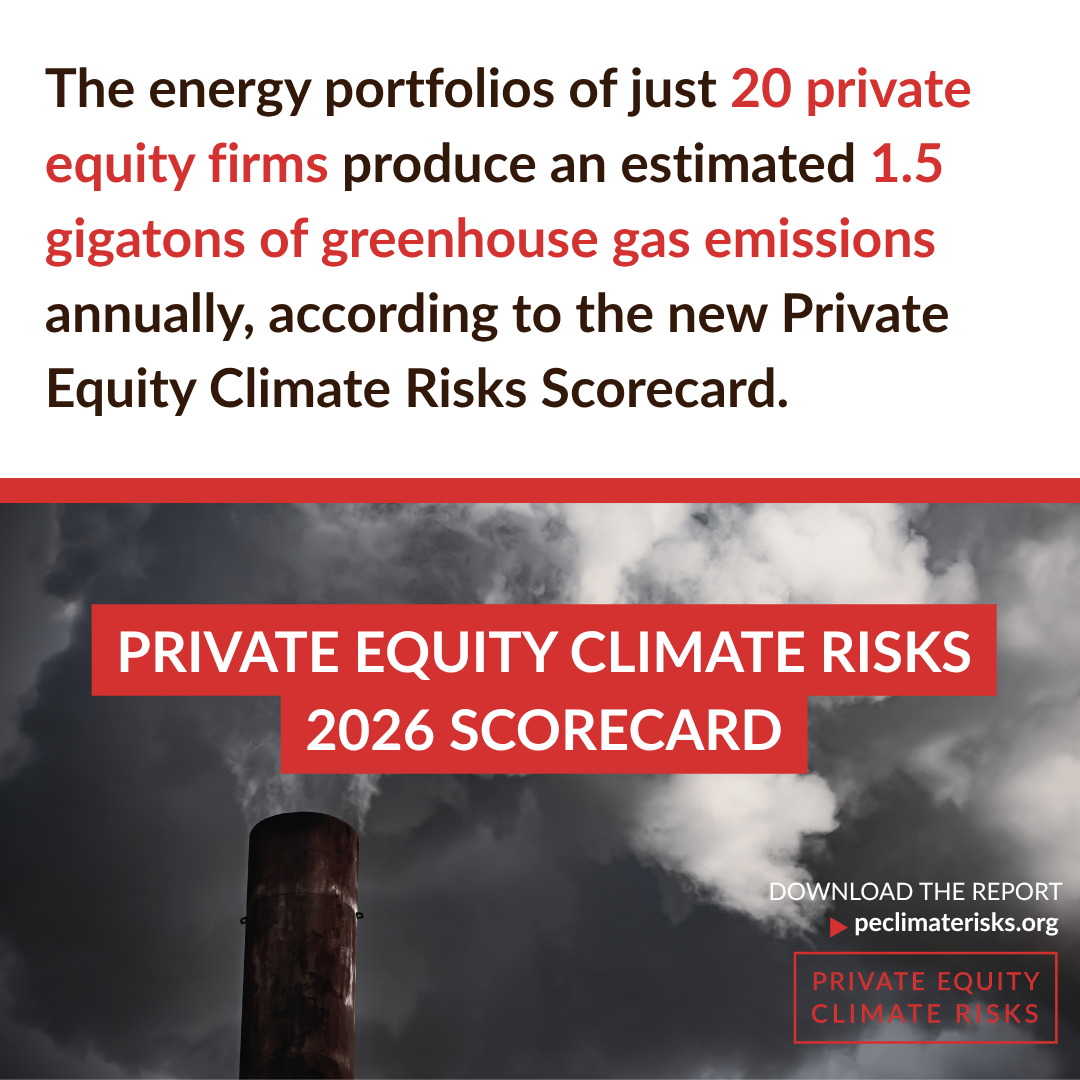
Global emissions are up. Private equity is a culprit – and so is the Oregon Treasury. Private Equity Climate Risks consortium has just published its latest scorecard and report , endorsed by 21 organizations working on climate, environmental justice, financial accountability, and consumer issues, documenting (pages 10-28) that: ⚠️ 20 private equity firms’ energy portfolios: are responsible for producing an estimated 1.5 gigatons of greenhouse gas emissions annually. include more than 1,000 assets: 244 energy companies 250 oil and gas fields 15,000 miles of pipelines 35 LNG terminals 13 coal terminals dozens of LNG tankers hundreds of fossil fuel power plants. The Guardian (9/15/2026) on the Private Equity Climate Risks report: World’s top 20 private equity firms produce more greenhouse gases a year than most countries, report finds : Firms manage $7.3tn in assets and could afford to transition away from fossil fuels yet invest in natural gas and coal-fired plants to power datacenters. “Private equity firms have emerged as the largest datacenter owners outside  of big tech.” (See the case study on data centers starting on p 25 of the report.) What about Oregon? ⚠️Six private funds, held by the Oregon Treasury, hold at least 473 fossil fuel assets. These firms are: Blackstone, Brookfield Asset Management, Encap Investments, EQT, Global Infrastructure Partners (GIP), Quantum Capital. All are in the Real Assets holdings. As Private Equity Stakeholder Project commented to the Oregon Investment Council (see Public Comment book of 9/2/2026 , page 8): Through existing OST fund commitments, OPERF likely has exposure to many of these 473 fossil fuel assets, which also create global climate risk. Some funds held by OST are making new investments in fossil fuels, pushing the pension fund further from Oregon’s Climate Resilience Investment Act (CRIA) goals and creating more risk for the fund. One example: BlackRock’s GIP. Oregon invested in GIP (Global Investment Partners fund), created to finance a new LNG terminal (see Is the Oregon State Treasury Supporting Environmental Racism in the Gulf South? Divest Oregon 9/26/2024). The fund is now managed by BlackRock and it plans to acquire AES, a massive US-based utility company that also backs 23 fossil fuel-fired power plants globally. If the AES deal closes, BlackRock’s GIP will nearly double its fossil fuel power plant portfolio to 50, spanning 11 countries.
August 6, 2026
“As a PERS beneficiary, I am horrified that my pension funds private prison contractors and ICE detention centers.” Three recent Letters to the Editor of The Oregonian voice deep disquiet that the Treasury invests in immigrant detention facilities and spyware that are internationally recognized as engaging in human rights abuses and are flagrantly violating constitutional rights – instead of constructive investments. In June 2025, Oregon Treasury data shows investment of $51 million in CoreCivic and Geo Group, private prison contractors, and Palantir, maker of surveillance software used by ICE against US residents. Divest Oregon has been asking the Treasurer for years : Why aren’t investments screened to comply with Oregon Investment Council standards? See the blog: Why is the Treasury still investing workers’ retirement in fossil fuels, ICE contractors, and surveillance technology? for the backstory. In May, Treasurer Steiner stated that Treasury used its shareholder power to vote against four candidates for Geo Group’s board of directors because it was not conforming to Treasury’s investment standards – but kept the stock: Treasurer Steiner is “ deeply troubled ” about ICE contractor Geo Group…but OST has been a shareholder for years. The Treasury is investing public employee money. It has a responsibility to the beneficiaries and to all of us to follow its own investment guidelines. The letters voice a strong call for change: PERS should divest from ICE-contract prisons ( PDF , The Oregonian 7/27/2026) “Human Rights Watch reports that 52 people died in the custody of U.S. Immigration and Customs Enforcement in the first 500 days of President Donald Trump’s second term…." “It is tempting to feel powerless about this senseless waste of life. But here in Oregon, we have an opportunity to make a difference. We can demand that the Oregon Public Employees Retirement System divest from The Geo Group and Core Civic, two of the largest for-profit private prison corporations, which contract with ICE to run immigration detention facilities.” Oregon shouldn’t invest in ICE prisons ( PDF , The Oregonian 7/31/2026) “As a PERS member, I am not comfortable profiting from other people’s misery, and I am confident that others feel the same." “Reduced public investments and increased public awareness could even make investments in Geo Group and CORE Civic less attractive. Oregon should lead opponents of the cruelty in this immigration crackdown, epitomized by these prisons." Divest PERS from ICE-contract prisons ( PDF , The Oregonian 8/3/2026) “As a PERS beneficiary, I am horrified that my pension funds private prison contractors and ICE detention centers." “Oregon State Treasurer Elizabeth Steiner said she was 'deeply troubled' by Geo Group’s practices, and that the Treasury had used its shareholder power to vote against four candidates for the company’s board. Has that vote had any noticeable effect? Will Geo Group change its business practices as a result? These companies might take notice if the Oregon Treasury began pulling its investments.” “Like the people of Minneapolis, Oregon Gov. Tina Kotek, Oregon Attorney General Dan Rayfield and Portland Mayor Keith Wilson stood up to ICE. This is the moment for our Treasury staff to show the same courage."
July 6, 2026
Photo by SpaceX on Unsplash In a July 1 article Reuters reported that Oregon Treasurer Steiner wanted guidance from the federal Securities and Exchange Commission (SEC) about SpaceX. How should pension funds handle the new company with the giant market valuation? SEC Commissioner Mark Uyeda answered Elizabeth Steiner in an interview in Reuters . One takeaway is his simple point that if you don't like the governance arrangements of a stock, don't buy it. A message from the SEC's Uyeda: If you don't like SpaceX's governance, don't buy the shares ( Reuters Sustainable Finance , July 1, 2026) Note: The Oregon State Treasury has $6.8 million in exposure to SpaceX through one public equity index fund and one global equity portfolio ( Portland Business Journal July 2, 2026). Divest Oregon has made the same point to Treasurer Steiner, repeatedly. For example, Treasurer Steiner posted on Facebook on May 6, 2026 that she is “deeply troubled” by the ways ICE contractor Geo Group fails to adhere to Oregon Investment Council (OIC) policy. Divest Oregon responded : The Oregon Treasury has held stock in private prison/immigrant detention contractors for years, in spite of well-publicized abuse. If a company is violating OIC policy the Treasury has an obligation to sell the stock. In fact, Treasury’s screening process can and should prevent purchasing or holding stock that violates OIC/Treasury standards. The SEC Commissioner quoted in the Reuters ’ interview about SpaceX also says pension funds have the duty and ability to do such screening: Question by Reuters to SEC Commissioner Uyeda: "You write that ‘If prospective investors have concerns with the governance arrangements, then their most powerful tool is to not purchase shares of the stock.’ But critics like some big pension funds say the fast-track addition of SpaceX to big indexes could make them unwilling buyers of the stock. What would you say to such critics? Response from SEC Commissioner Uyeda: "Large pension funds have choices with respect to ​their investment decisions as part of their fiduciary duty to the plan. While index funds may have certain conveniences and low costs, there is a trade-off to outsourcing securities selection to a third party. There are alternatives, such as selecting a fund that follows a different index or is actively managed, or engaging in customized direct indexing that would provide more control over the portfolio.”
May 19, 2026
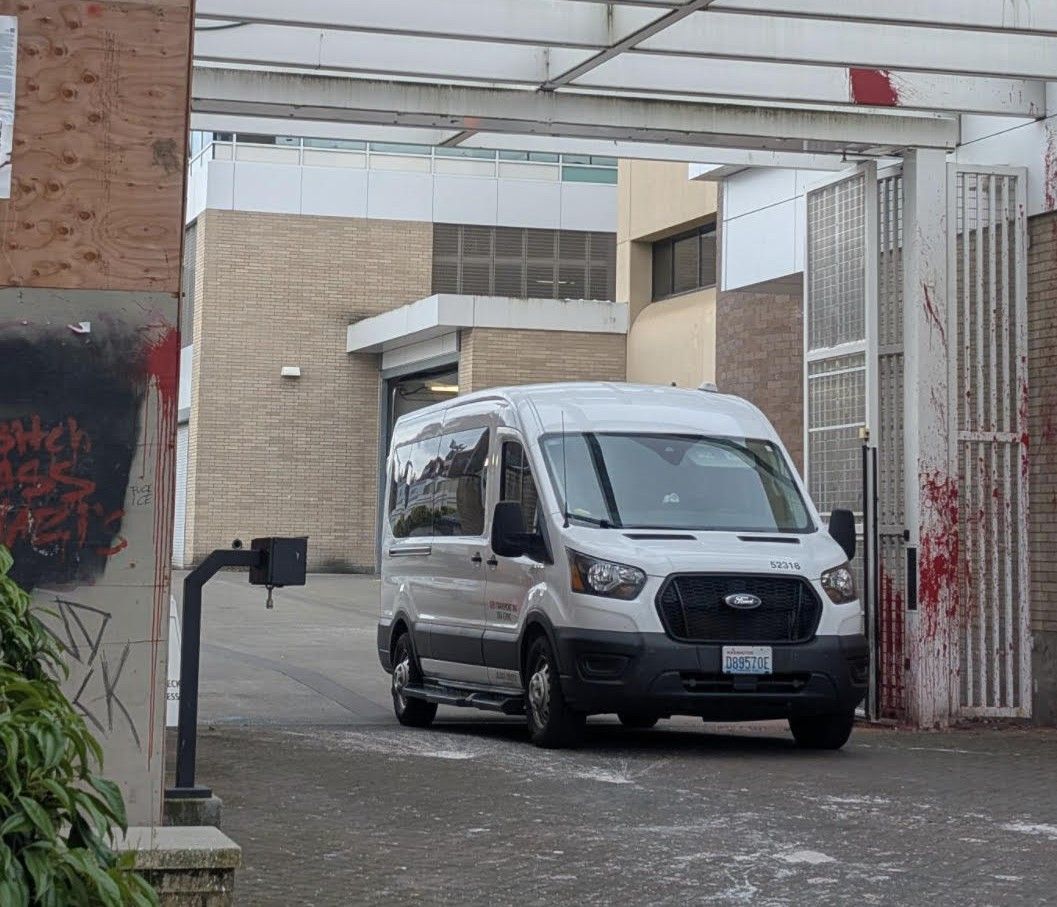
A Geo Group van leaving the Northwest ICE Processing Center in Portland Oregon. May 2026
April 9, 2026
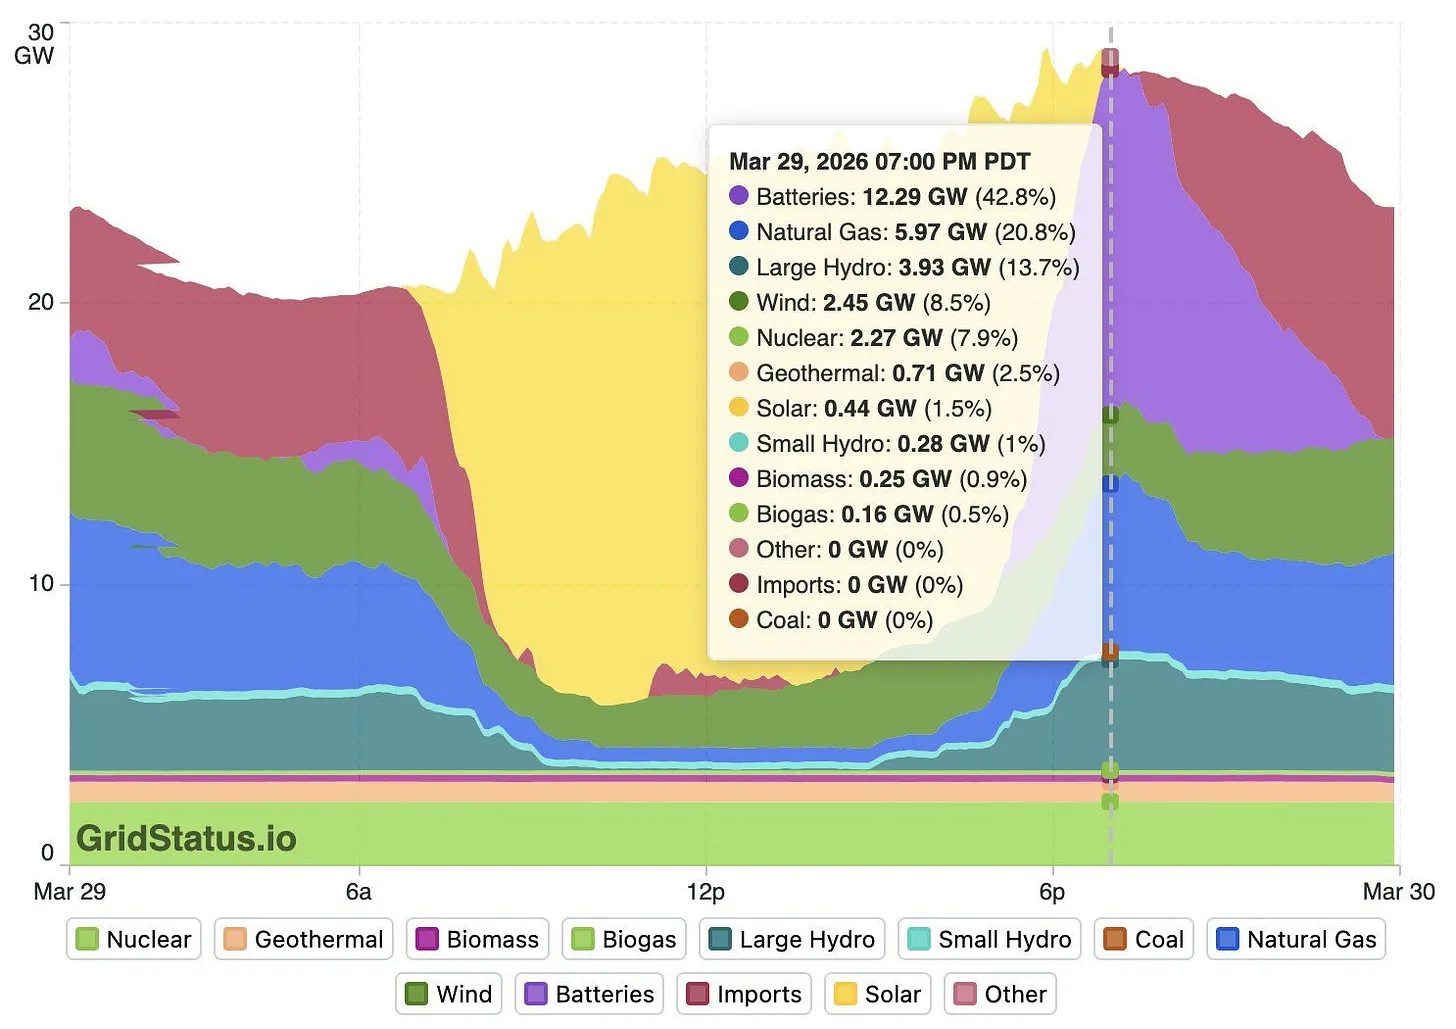
At the March 2026 OIC meeting, John Goldstein from Goldman Sachs spoke of the strength of renewable energy stocks (recap in Net Zero Investor 5/3/2026 ). Bill McKibben shows us how the sector is evolving with battery technology advances. Night into Day ( The Crucial Years substack 3/30/2026): “For the first time, the United States now has the capacity to supply 100% of domestic energy storage project demand with American-built systems,” said Noah Roberts, executive director of the U.S. Energy Storage Coalition. “That is a fundamental shift from where we were just a year and a half ago, when the majority of battery storage systems were imported.” “Already, the U.S. has enough capacity to meet demand for finished grid battery enclosures…. By the end of this year, the U.S. will also achieve self-sufficiency in a higher-value part of the supply chain: the battery cells themselves. It’s a major industrial coup that is bringing thousands of high-tech manufacturing jobs to communities across the country.” Solid-state batteries are becoming a possibility; they promise to solve several problems: “Batteries are now being tested by multiple companies that can go 800 miles on a single charge….“In September, Mercedes drove a modified EQS over 1,200 km (745 miles) using 106 Ah solid-state battery cells supplied by US-based Factorial Energy. Factorial launched the first commercial solid-state battery program in the US …earlier this year.” The Finnish company Donut Labs shows where this is heading: “The Donut batt can charge to full in five minutes…; has a practically unlimited lifespan (100,000 charging cycles); is unaffected by heat and cold (-30C to 100C); and contains no rare earth, precious metals or flammable liquid electrolytes. With all that, Donut Lab says it will be cheaper to produce than conventional lithium-ion batteries…” “And the technological miracles are only beginning. For instance, Christopher Mims reported last week in the Journal on a new round of ‘thermal batteries that store solar power as heat instead of electricity, perfect for use in high-temperature industrial processes.’” “Marija Maisch was reporting in January that…salt-based batteries are nearing price and performance parity, if not for cars then for utility scale batteries.” And this chart shows the surge of batteries coming online as solar installations lose sunlight. Night into day.
March 17, 2026
A question from Divest Oregon, a coalition of a hundred organizations with strong PERS representation, remains unanswered: What screening process does the Oregon State Treasury (OST) use, if any, when investing PERS funds or choosing investment managers? Is the Treasury screening investments in fossil fuel companies? Andrew Bogrand, Divest Oregon’s Communications Director, spoke at the Oregon Investment Council (OIC) in January 2026. He noted that investment in fossil fuels contributes to global instability, using Venezuela as an example. (See this blog .) The current Iran war emphasizes this point. Andrew regularly comments on the ties between insecurity and fossil fuels as a policy lead for human rights and natural resource justice at Oxfam. The argument that fossil fuel investments are a sensible diversification of a portfolio has long been outdated. But looking at the most recently published June 2025 public equity and fixed income data, the Treasury is still investing in fossil fuels. Under fiduciary duty and the Climate Resilience Investment Act ( CRIA ), the Treasury must move to alternative investments that align with the reality of climate change and a rapidly destabilizing world. Is the Treasury screening investments prone to legal liability, human rights abuses, or reputational risk? In an April 2023 report , Divest Oregon called out the Treasury's investment in private prisons and surveillance technology as context for the question: Does the Treasury have a screening process? If so, what is the screening process? One example given in that report was the NSO/spyware technology that OST heavily invested in. The Guardian reported extensively (2022) on the OST’s investment in NSO/Pegasus spyware: “However, it now appears that the Oregon pension fund, one of the most prominent in the US, gave its tacit approval over an investment in NSO several years ago – at a time when security researchers were already publicly raising alarms about the company.” In a more recent report, Oregon Treasury’s Investment Screening Failures ( October 2025 ), Divest Oregon again questioned the Treasury’s investment screening process. Examples of questionable investments included GEO Group, CoreCivic, and Palantir. Investments in GEO Group and CoreCivic fund private prison contractors and ICE detention centers. Investment in Palantir funds ICE surveillance software used against US residents. See additional information below for each of these companies. The most recent public data ( June 2025 ) shows that the Treasury continues to invest in these private prison and surveillance technology companies with a long history of human rights abuses and legal vulnerability. These companies are central to the current federal administration’s construction of a police state and its massive violation of due process. See Trump’s Mass Deportation Campaign ( The New Yorker 3/15/2026). For example: Recent private prison contractor GEO Group news: In February 2026, the Supreme Court found that GEO Group, a private prison operator running an Immigration and Customs Enforcement (ICE) facility, cannot claim governmental immunity from lawsuits for violating human trafficking laws, even if those violations were under government orders. Recent surveillance technology company Palantir news: In Portland, now, Palantir’s Elite app is being used to identify potential deportation targets, generate dossiers on individuals and provide a “confidence score” on the person’s address. ( The Guardian 3/13/2026) Why should the Treasury screen its investments? Screening is necessary to avoid investments that contravene Treasury standards, OIC policy, legal standards including fiduciary duty, or Oregon State law. For instance: The Oregon Department of Justice has recently opened an inquiry as to whether OST investment in companies with contractual ties to ICE violates the Oregon Sanctuary Promise Act of 2021 . The CRIA Act of 2025 mandates that the Treasury: -- “actively analyze and manage” climate risk to the portfolio -- report on its progress toward investing in public equity holdings that incorporate the tenets of a just transition in their overall priorities and portfolio
February 18, 2026
Part 2: Building on Oregon State Treasury’s 2025 Progress toward Net Zero Emissions Divest Oregon applauds initial action, offers recommendations for future reporting, including the use of multiple metrics
February 18, 2026
Part 1: Building on Oregon State Treasury’s 2025 Progress toward Net Zero Emissions Divest Oregon applauds initial action, offers recommendations for future reporting, including the use of multiple metrics
January 29, 2026
Thanks to the passage of CRIA and the Coal Act, Oregon is moving toward a more transparent assessment of climate-related risks, engaging with asset managers and companies, and identifying climate-positive investments. OPERF has nearly $90 million invested with Exxon, $40 million in Chevron, and $5 million in Shell. Can the Treasury hold these companies accountable and protect the wider portfolio from major conflict exposure? Following is incisive testimony to the January 2026 Oregon Investment Council by Andrew Bogrand, Divest Oregon’s volunteer Communications Director. For over five years, the Divest Oregon coalition has encouraged the Oregon State Treasury to take seriously the financial risks associated with fossil fuel investments, particularly within the context of the wider energy transition. Treasury, as well as the Oregon Investment Council, has listened and responded. Thanks to the 2025 Climate Resilient Investment Act (CRIA) and the 2024 Clean Oregon Asset Legislation (COAL) Act , our state is moving toward a more transparent assessment of climate-related risks, engaging with asset managers and companies, and identifying climate-positive investments. Of course, much of the work remains. In the spring of 2025, Divest Oregon provided testimony to lawmakers in Salem about the coalition’s support of CRIA. We shared how the bill would help Treasury address “new economic realities, where geopolitical contestation…and natural resource competition will upend the financial logic of passive investing.” A year later, this statement rings painfully true. We stand on the precipice of resource-driven conflicts in Venezuela, Greenland, and Iran. We are witnessing a deterioration of the international rules-based order, which will come with serious financial implications. This breakdown is not random. Chevron has played “the long game” in Venezuela, spending millions lobbying the Trump administration and positioning itself to profit following the US invasion. Shell is seeking a multi-billion gas project following the illegal ouster of President Maduro, which presumably also secured ExxonMobil’s interests – not in Venezuela, but in neighboring Guyana . And, the American Petroleum Institute, an industry lobby group including Chevron, Shell, and Exxon, recently pledged to “stabilize Iran” if the regime is ousted there, too.  Of course, whether these companies will profit from this new era of resource colonialism remains unclear. Darren Woods, the CEO of ExxonMobil, said bluntly that Venezuela is “un-investable.” Chevron has also acknowledged that any future work in Venezuela will require extensive guarantees and long-term stability, conditions which remain absent. Despite all the money spent on lobbying, the oil market remains volatile and these companies will likely seek taxpayer support and sanctions relief for risky bets abroad Treasury has nearly $90 million invested with Exxon, nearly $40 million in Chevron, and over $5 million in Shell. Now the question is how to hold these companies accountable and protect the wider portfolio from major conflict exposure. Not all energy companies are equal. In contrast to Chevron, France’s TotalEnergies, which Treasury also owns, has no intention to enter Venezuela despite its operations in nearby Suriname, presumably worried that their presence could make a humanitarian crisis worse or even directly fund human rights violations. If Treasury is serious about engagement, as set forth in CRIA, now is the time to exercise this commitment toward the most politically-exposed companies. Extraction by military force pushes the absolute boundaries of the social license to operate and undermines other holdings in Treasury’s portfolio. Companies have a major and well-recognized responsibility to avoid contributing to war. This responsibility is rooted in the UN Guiding Principles on Business and Human Rights as well as in international humanitarian law. Companies are expected to conduct rigorous human rights due diligence to ensure that their operations, supply chains, and technology do not fuel or contribute to conflict. If companies like Chevron and Exxon fail to respond to engagement along these lines then divestment is both an appropriate business decision -- and the right thing to do.